Showing posts with label India. Show all posts

Wednesday, February 22, 2017

Louis-Vincent Gave translates geopolitical events of 2016 into investment opportunities for 2017

Louis-Vincent Gave discusses with Erik Townsend:

China Reflation Trade
Is Chinese Growth Rolling Over?
Will Trump Get a Weaker US Dollar?
Brexit and the Future of the European Union
Philippines and Rodrigo Duterte
Rise of the Chinese Empire
India and the Indian Currency System
Opinions on Stocks and Bonds
Investment Themes for 2017
Risks for 2017

I thought the insight into Asia, specifically the Phillippines under Duerte, Xi Jinping's imperial ambitions, and the role of corruption within an developing economy (India) were particularly useful.

Wednesday, September 30, 2015

Rani Mullen and Cody Poplin on the Battle for Access and Influence in the Indo-Pacific

Good piece in Foreign Affairs titled The New Great Game - A Battle for Access and Influence in the Indo-Pacific by Rani D. Mullen (Associate Professor in the Government Department at the College of William and Mary, Virginia and Director of the Indian Development Cooperation Research (IDCR) at the Centre for Policy Research, New Delhi, India) and Cody Poplin (Research Assistant at the Brookings Institution in Washington, D.C. and an Associated Editor of Lawfare).
 
Excerpt:
Huge stakes are involved. Trade, energy, and geostrategic imperatives are driving both Chinese and Indian ambitions. Between the Indian and Pacific Oceans lies the main choke point of world commerce, the Malacca Strait. Today, more than half of the world’s container traffic and one-third of all maritime traffic crosses the Indian Ocean and passes through this point and into the South China Sea. To understand the scale, consider that roughly two-thirds of South Korea’s energy supplies, nearly 60 percent of Japan’s energy supplies, and 80 percent of China’s crude oil imports arrive over this maritime route. Meanwhile, 75 percent of India’s energy supplies cross the Indian Ocean.
 
China has long felt trapped by what national strategists have termed the “Malacca Dilemma”—that China’s access to the greater Indo-Pacific is limited to one main pass and that, to reach that pass, its ships have to travel over the South China Sea, which is a mess of overlapping territorial claims from countries in the region. And so over the last decade, China has sought to secure its access to the critical sea lanes, including by creating artificial islands with airfields in the South China Sea [6] and declaring an expansive and novel Exclusive Economic Zone—one that is far larger and includes far more prerogatives than permitted under The United Nations Convention on the Law of the Sea—over the area. From this perspective, Chinese Vice Admiral Yuan Yubai’s recent, and rather incendiary, declaration that the South China Sea “belongs to China” makes strategic sense: It is after all their path to the greater Indo-Pacific.
 
Plenty of ink has been spilled over the South China Sea, and appropriately so. But the South China Sea is just an example of a larger game that is already underway.
 
Along with creating routes to and around Malacca, China has provided soft loans to Bangladesh, Pakistan, Myanmar (also called Burma), and Sri Lanka for everything from highways, to power plants, to seaports. All of this has been part of China’s Maritime Silk Road strategy, which is meant to bind countries in the Bay of Bengal and the Indian Ocean closer to the Chinese economy as well as to build trade routes from China through their territory to the Indian Ocean, which would allow China to avoid the Malacca bottleneck. Yet this approach has been hurt by China’s more muscular activities in the South China Sea, which have scared the country’s smaller neighbors into closer alliances with India, Japan, and the United States.
 
As China has become more assertive, India has focused on its own rapidly growing need for access to critical sea lines and opportunities for trade and investment. In 2011, maritime trade constituted close to 41 percent of India’s overall GDP; the figure reached 45 percent in 2015. India now imports about three-fourths of its oil through the Indian Ocean. India fears that China, relying on its alliance with Pakistan, might encircle India on land and at sea. For Indian strategists, it doesn’t seem far-fetched that China would use its increased maritime capability to create a zone of naval exclusion that stretches from the South China Sea to the Persian Gulf.
 
To counter such encroachment, India, which was the largest recipient of global foreign aid until the early 1990s, has started to dole money out. The country now has more than $12 billion in open lines of credit and dozens of major development projects in foreign countries. Although Indian aid equals just a fraction of Chinese aid in the region, India hopes to use its funding, increased trade focus, military diplomacy, and cultural ties—its so-called Act East policy—to maintain and expand its leverage over the Indian Ocean Rim states to preclude a more permanent Chinese presence in those waters.
 
This, in a nutshell, is the New Great Game [7].


My personal view is that Sri Lanka will favour China's influence as the resentment in Colombo towards New Delhi is palpable, the United States will tilt towards India for balance of power reasons in reaction to the Asian hegemon and the fact that it is angry over relentless Chinese cyber-attacks and bluster and India will lever a more assertive and muscular Japan since the Abe government  has renounced the pacifism that it embraced post World War II. Any Indian attempt to increase its profile be it through soft or hard power will be dependent upon who is in power in New Delhi. It is not a coincidence that the Indian state has hit beneath its weight for much of its existence thanks to those who have governed it at the national level.


Thursday, November 21, 2013

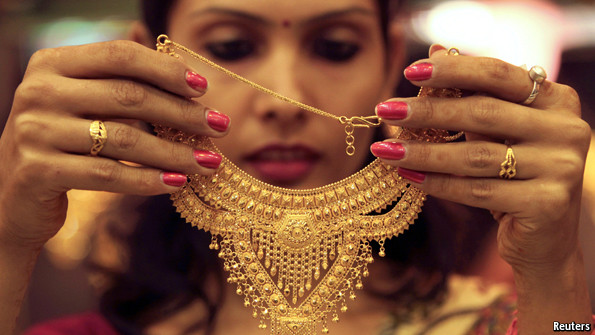
Indians and the barbarous relic

From The Economist:
The second reason why gold is popular is that it allows you to bypass a lot of India’s legendary red tape. Opening a bank account in India is bureaucratic hell. Gold, on the other hand, is widely accepted without any documentation. It is also a fine way to store wealth without paying tax—along with property, it is the asset class that the authorities struggle to track. Some reckon that the huge boom in gold has closely tracked the boom in political corruption over the past decade.
At the individual level, then, the gold craze makes sense. But in aggregate it is a disaster for India. Imports of bullion impose a massive strain on its balance of payments—amounting to $54 billion in the year to March 2013. India’s current-account deficit reached an alarming 4.8% of GDP that year, and just over half of the gap was due to gold. Gold also diverts savings out of the formal financial system, where they can be harnessed for investment. Thus while India’s overall savings rate is high and on par with those of Asia’s “tiger” economies, half of those savings are now diverted into physical assets. (emphasis added)

Reference
F., P. "Why do Indians love gold?." The Economist, November 20, 2013. http://www.economist.com/blogs/economist-explains/2013/11/economist-explains-11 (accessed November 21, 2013).


Wednesday, July 24, 2013

Executing China's String of Pearls Strategy

Back in 2009, Chris Devonshire-Ellis wrote:
China’s “string of pearls” strategy appears to be taking another step forward as Beijing increases ties with the Sri Lankan government. The strategy, which was the subject of a 2005 U.S. China Commission report to Congress, is driven by China’s need to secure foreign oil and trade routes critical to its development. This has meant establishing an increased level of influence along sea routes through investment, port development and diplomacy.

To date, China’s investments extend from Hainan Island in the South China Sea, through the littorals of the Straits of Malacca, including port developments in Chittagong in Bangladesh; Sittwe, Coco, Hianggyi, Khaukphyu, Mergui and Zadetkyi Kyun in Myanmar; Laem Chabang in Thailand; and Sihanoukville in Cambodia. They extend across the Indian Ocean, Sri Lanka, the Maldives, Pakistan’s Gwadar Port, and in islands within the Arabian Sea and into the Persian Gulf.

Not surprisingly, both the U.S. and Indian governments are concerned, part of these developments include the upgrading of airstrips, many supported with military facilities, such as the facility on Woody Island, close to Vietnam. These developments mean that the balance of power within the Indian and Arabian Gulf has now shifted away from the traditional Indian government management, backed up with U.S. military strength, but to China, backed up with regional diplomatic ties that dispense with the need to engage with either power. (Devonshire-Ellis, 2009)

China's "String of Pearls" Strategy

Fast forward to 2013 (H/T http://chindia-alert.org/ ) :
Sri Lanka has finalized a $1.43 billion deal with China Communications Construction Co Ltd (601800.SS) to build a city on a 230 hectare site that will be reclaimed from the sea, the head of the state-run Ports Authority said on Wednesday.

The site is next to the island nation's main Colombo port and Colombo's historic Galle Face Green seafront. It is also close to where Shangri-La Hotels Lanka Ltd, a subsidiary of Hong Kong-listed Shangri-La Asia Ltd (0069.HK), is building a 500-room hotel.

"The Chinese firm will invest in reclaiming the land and infrastructure of the port city," Priyath Wickrama, chairman of Sri Lanka Ports Authority, told reporters. "It will be given around 50 hectare of reclaimed land on a 99-year lease for its investment."

The 39-month long construction project will start in September, Wickrama said, adding the city would include eco-parks, residential areas, offices and shopping malls.

Since the end of a nearly three-decade war in May 2009, the Indian Ocean island nation has been spending heavily on infrastructure, including ports to attract foreign investments to its $59 billion economy.

It has already created new land near the proposed port city as part of its expansion of the Colombo port to double its capacity by 2015.
“India is too large a country to be encircled” said M.K. Narayanan, the incumbent West Bengal governor, in 2010 (Suryanarayana, 2010).
The opposite appears to be the case thus highlighting what international relations analysts have surmised for some time: India punches beneath its weight geopolitically. 
In retrospect, going as far back as 1992, we can see George K. Tanham's report, "Indian Strategic Thought: An Interpretive Essay" to reflect the shortcomings of the Indian system.

So is Asia headed towards Chinese hegemony? Extrapolating is dangerous; China's rise appears secure but not as simple as it sounds. Shinzō Abe's landslide victory provided him with the mandate he truly craves. No, it isn't about implementing Abenomics and its three arrows for economics has never been Abe's passion, it is about restoring Japan to its glory as a muscular and militarized nation.

References
Devonshire-Ellis, C. (2009, March 18). China’s string of pearls strategy. China Briefing, Retrieved from http://www.china-briefing.com/news/2009/03/18/china’s-string-of-pearls-strategy.html   Aneez, S., Sirlal, R., and Holmes, D.(ed.) (2013, July 24). Sri lanka teams up with chinese firm for $1.4 billion port city. Retrieved from http://www.reuters.com/article/2013/07/24/us-srilanka-port-city-idUSBRE96N0NU20130724  
Suryanarayana, P. S. (2010, September 26). ‘india should not punch below its weight'. The Hindu. Retrieved from http://www.thehindu.com/todays-paper/tp-national/india-should-not-punch-below-its-weight/article796223.ece
Tanham, G. K. (1992). Indian strategic thought: An interpretive essay. In Santa Monica, CA: RAND. Retrieved from http://www.rand.org/content/dam/rand/pubs/reports/2007/R4207.pdf

Friday, May 13, 2011

Double, double toil & trouble -- volatility burn & assets bubble

Hopefully the Bard won't be turning over in his grave with the co-opting and changing of the famed lines from Macbeth.
Who do the 3 Witches represent today?
If the scene with the three witches can teach us anything about the market activities of the fortnight past -- from the commodity sell-off on May 5-6 to the rebound in risk off strategies this week in light of market concerns about Greece's (in)ability to meet its debt obligations, it is that the three antagonists of the financial markets of 2011 -- China's mercantilism; Eurozone's sovereign debt overhang; and financial capital flows abetted by the America's easy money policy -- are contributing to the whipsaw volatility and asset price frothiness that the modern investor should now take as "normal".

The symptoms are to be seen everywhere.
Commodity currencies
Let's recap where we have been (in the medium run) by starting at home with what the world's investors view as an archetypal commodity currency: the Canadian dollar. In a previous post, I argued that while CAD was seen as a petrocurrency, it didn't necessarily entail a steady upward movement beyond parity with USD whenever there was a concomitant rising of oil prices; my contention was that this was due to the Canadian economy's inability (at the firm level) to absorb the cost of a higher terms of trade. Moreover, Canadian consumers do not benefit from a strong loonie unless they shop across the border as Canadian retailers are uncompetitive and rarely adjust prices for to match those of US retailers. I suggest considering the framework below when forecasting CAD, AUD, and other so-called commodity currencies especially given that flow of funds, technical and sentiment factors outweigh PPP in the short-medium term.


$CAD vs. Oil
Here is an update to some of that earlier analysis where we see the $CAD relationship versus the price of oil (specifically NYMEX futures 1 month forward) in two segments: 1990s (top chart) and 2000s (bottom chart).


Remembering the '90s
Evidently, the relationship was weak in the 1990s and strengthened during the 2000s. Recall that during the 1990s the world was supposedly "Drowning in oil" (The Economist, March 4, 1999), there was a meaningful strong dollar policy in the aftermath of the Plaza Accord during the Clinton Administration, and Canada --while getting its fiscal house in order during Jean Chrétien's time as Prime Minister -- still had a manufacturing sector (to speak of) that was addicted to a falling loonie as a means to remain competitive and export to the important American market.
$CAD = function of Oil and Stock Market
In providing some more colour to this relationship, my economics professor from business school, Perry Sadorksy, suggested that I consider the relationship with Canadian stocks in addition to oil as an independent variable driving $CAD.
Here is a time series from the 1990s to 2011YTD.


Taking this a step further, here are the multiple regression results of the above relationship (click on the image to the right to expand):


To add some rigour to the analysis, Professor Sadorsky computed dynamic correlations between the S&PTSX composite, the $CAD exchange rate and oil during the sample period.

Takeaway: Correlations between these assets have increased in the past 10 years - while portfolio diversification is a positive, one would not get far diversifying risk amongst these assets during times of stress.


What does the addition of the Canadian equities index to the analysis in the multiple regression tell us? Professor Sadorsky used a vector autoregression to generate impulse response functions for the S&PTSX composite, oil and $CAD exchange rate. Basically, this approach looked into the dynamic interaction between the variables -- what is the effect on the variables in the system to a shock to one of the variables? -- and here the contention that oil's increased influence over time remains viable.
Takeaway: Oil has had a greater impact on the S and PTSX index in the post 2000 period.


What can the $CAD relationship show?
Fundamentally, capital is flowing to the areas where there is the best opportunity for a risk adjusted return --this is nothing new-- even when investors have not accurately considered the risk situation; the flow of financial capital to the lower cost developing world coincided with the steady demand for commodities (due to heightened development in those regions) which subsequently has led to a steady appreciation of commodity currencies such as CAD and AUD. Canada is correctly perceived as a hewer of wood and drawer and will be hard pressed to stave off a serious bout of Dutch Disease unless there is enlightened industrial policy at the Federal and Provincial level. Canada is not Norway: meaningful discourse on the role of the state in providing an effective policy shock absorber to potential supply shocks remains unlikely.
In my opinion, it is in the casino-like nature of financial capital flows that will to lead to a continued boom and bust cycle as advanced economies following the Anglo-Saxon model of neoliberal development have been increasingly de-industrialized thanks to many of those sectors being "exportable".
An obvious retort to this point of view would be why now given that the past two decades has seen none of this prior to The Great Recession -- a period that has mythically been described as The Great Moderation.
In answering this, we must remember that the reduced macroeconomic volatility in the post Cold War period was not due to the factors as described by Ben S. Bernanke. Instead, think of the downward pressure of wages in an aggregate sense that was influenced primarily by the full entry of, China, a true economic dragon --with its vast labour pool and incomparably competitive manufacturing sector; and secondarily by the cautious entry of India, a once plodding elephant now surging tiger, where the country's multinationals also have had access to a relatively low cost (on a global scale) english speaking skilled labour pool. India's success would not have been possible without the post-industrial pipes --broadband technology-- which made the idea of IT servicing "exportable". Meanwhile, China's success came as a result of the technology transfer combined with an insatiable demand for consumption of affordable goods by Americans who were increasingly becoming more indebted in order to keep up with the Joneses in maintaining an affluent and aspirational lifestyle.
The downward pressure on wages globally made inflation targeting domestically more effective by central banks in the advanced economies. That job will become more challenging in the coming decades.

Think Again

In retrospect, the massive capital expenditures during the 1990s which at the time was incorrectly perceived as the "technology or dot.com" boom was rather the catch up of long overdue business investment.


Traditional view of bubble formation
Conventional neoclassical economic analysis argues that American monetary policy -- we focus on America as the world's largest economy and Fed Funds rate as arguably a proxy for a "global interest rate" for adherents of the Mundell-Fleming model view-- had been too loose since the terrorist attacks of September 11, 2001, mastermind by America's (now vanquished) nemesis, Osama bin Laden.

This loose monetary policy, in turn, led to the real estate bubble that was popped in the aftermath of the 2007 credit crunch, and prior to the full blown financial crisis in 2008. For an illustration of the conventional view, see below, where the Fed Funds rate is graphed against the Taylor Rule.


While I have neither bought into the orthodoxy of the primacy of monetary policy nor been a fan of John Taylor's policy views, there is relevance to the point that sub-optimal interest rates -- specifically to the low side-- leads to greater risk taking, over investment in risk assets (e.g. real estate, stocks, commodities) and the severe mis-allocation of a nation's resources over the short to medium term.


Spain and Ireland, under the EMU, are in the throes of adjusting after many years of sub optimal policy courtesy of the ECB.
And Greece's travails in meeting its debt obligations --absent significant fiscal transfers from primarily Germany and the surplus nations of the Eurozone--will ensure a pathway of debt default to restoring drachmas.

I have argued in a previous post that the diminished purchasing power of American workers has been brought to light in the aftermath of the Great Recession because of a lack of access to credit and the paying down of debt in personal balance sheets. Robust economic growth in America is possible if the access to credit is restored to the consumers directly and the small businesses who see it as a lifeline; without it the story is one of sub-trend growth going forward.

Enter The Dragon: China's Mercantilism
Now, with the ascent of China in particular, we must expect a return to the business cycles of hard landings in the West and be satisfied with sub-trend growth in the most advanced economies due to the difficulties of households in coping with the boom and bust of foreign originated supply shocks and the realities of balance sheet repair.

Let's revisit China's mercantilism: the yuan remains undervalued by most measures; cleverly executed import restricting and export subsidizing policies are reflected through massive foreign exchange reserve growth. The bulk of the capital, in turn, is funneled through China's rentier class and those just beneath on the social ladder --think of the friend's of the People's Party-- where the rocketing of Chinese liquidity has fed into the inflating of real estate bubbles.

Why has this shown up in Chinese real estate and not the stock market?
This is a flavour of the month issue; the current cycle has seen real assets in general and commodities in particular as the asset class of greatest interest to investors and speculators. Chinese authorities skilfully sterilize the monetary effects of reserve accumulation but will find it increasingly difficult to maintain such actions over the longer term as the central bank struggles with the asset as well as goods and services price inflation genie after having raised reserve requirements for the fifth time in 2011.

There is popular notion in the financial press that "surplus countries are stealing growth from the deficit countries and not allowing them to adjust to external and internal disequilibrium" which I think --while true in a superficial manner if one believes in the equilibrium concept-- masks a greater fault in terms of economic policy on the part of the now debtor nations. History has shown that overreach via debt portends the fall of empire.


Mercantilism was successful for Britain when the sun didn't set on the British empire so why shouldn't China pursue this policy? It has been a "success" while maintaining an export based macroeconomic model which helps it increase its hard power through an increasingly muscular military. This helps bolster the CPC position through overt nationalism and permits the access to inputs vital for China's continuing growth.


But no growth story is exponential forever without adjustments and corrections.
How China affects the US (and the rest) today:
Consumers feel the pinch every time they fill up the gas (petrol) tank and the cheap goods at WalMart are now getting a bit dearer:


But China will be slowing down:


Source: Sacha Tihanyi, Senior Currency Strategist & Mark Ellerbeck, Director - Scotia Capital
Even the outsourcing story is getting more expensive:


Loose U.S. Monetary Policy won't save housing
In thinking of the United States, notwithstanding the positive air of relief in a post bin Laden world, the unwinding from the real estate bubble still has some way to go:


Source: Barry Ritholtz's blog, The Big Picture

Alternative view on bubbles
It is important to break things down to the basics here: a capitalist economy has two sets of prices: one for assets, the other for goods and services. They do not necessarily move together -- that should be obvious through empirical observation and does not require a peer reviewed journal with graduate level mathematics to substantiate the claim.

When consumers hear a central bank's inflation figures, there is bewilderment at how understated it seems. But fundamentally, inflation for policy makers is the growth rate of an index of prices of goods and services not assets.

The fact that central banks do not explicitly target asset prices is a failing of the current dominant paradigm of economic thinking because we live in a credit economy; in a fractional reserve banking system banks have the ability to create money and the notion of "what is money" has moved on considerably from the time of Jevons, Walras and Marshall. There is sometimes a belated attempt to talk down asset prices through moral suasion of central bankers (e.g. "irrational exuberence") but it is often left to the tinkering of fiscal policy to do the job where the influence of politicians weighs heavily with short term opportunism trumping long term reason.

For all of its flaws capitalism remains the most dynamic economic system but a society must come to terms with the form of capitalism to embrace in order for it to function in its interest. However, but one thing is undisputed: asset bubbles are intrinsic to capitalism: they are driven by economic actors who lever up in order to buy more assets with rising prices with the intention of selling for a profit. The story of real estate always rising is taylor made for the Greater Fool Theory; what happens when the bubbles bursts is a potential debt deflation dynamic.
It need not be this way. Asset bubbles are often not as noticeable due to the countervailing forces of reasoned policy, the power of the state, and sustainable growth in line with the real wage appreciation. When the former is not in place, the crash occurs.
What, in 2008 was incorrectly attributed as a Minsky moment is actually a continuation of a Minsky half century (as described by L. Randall Wray). For Minsky to get a greater following in policy circles would require more scholars to expand on his ideas in an persuasive and rigorous fashion because, unfortunately, his writing style is not engaging enough for the average analyst to read and the layperson to comprehend. If you have picked up a copy of "Stabilizing an Unstable Economy" then you would agree with me.

What is so interesting in the current situation are the opposing forces:
commodity and asset inflation driven primarily by development in the BIC of the BRIC nations --think of this leading to a higher velocity in terms of the quantity theory of money-- and abeted by the Federal Reserve's loose money policy in the growing surplus and/or developing nations
contrasted against
the long-term deflationary trends of balance sheet repair and aging demographics leading to lower growth in the developed industrialized nations.

Add to the mix the never ending economic policy root canal that is the Eurozone sovereign debt crisis and you can observe a further fracturing of the growth story in the developed West.

In aggregate, this adds to the continued volatilty of markets as finance capital continues to seek the best risk adjusted return possible free of capital controls. Asset bubbles won't go away; they are an intrinsic part of the system we have--our leaders and policy makers must decide the beest means to deal with them.

Fearless forecasts


  • CAD, AUD weakening in the short run in light of reduced demand for commodities against a slowing China and India struggling to tame inflation.

  • EUR correlated to the politics of EMU: will fiscal transfer be enforced or will the charade of EFSF morphing into ESM continue ad nauseum?

  • Volatility in EURUSD and the crosses will continue until fiscal union is formalized and the debtor nations are willing to lose some sovereignty..

  • GDP contraction on the back of supply shocks as consumers in advanced economies adjust to the burden of higher gasoline (petrol) costs against the inelastic demand of an oil based economy; lower consumption, fiscal retrenchment at the government level will not be counterbalanced by business investment.

Monday, September 27, 2010

Commonwealth Games 2010: Choices after the circus is over

The road forward?

There is no easy path forward, no prescriptive panacea to rid the nation's of its deficiencies; uneven development is not simply the fault of the ruling class --undoubtedly, individual responsibility plays a role-- but they must be retrospective in what has worked and what has not in proposing a feasible future so that reality can match hyperbole in terms of the country's future.

Education

When Jawarharlal Nehru, India's first Prime Minister, evoked the nation's "tryst with destiny" he subsequently embarked on creating world class tertiary education at the expense of sound primary and secondary systems. The result was a never ending brain drain since 1947 and to date, 35% of the population remain illiterate while some 15% of Indian students reach high school, and 7% graduate.

There are those who criticize the great unwashed and complain of the indigence and indolence of India's teeming masses, but surely, this is short-sighted? Is it not the ignorance of the underclass who have received either poor or non-existent schooling in the vital formative years that is of greater concern? Ignorance begets ignorance for when a proper education is not received, it is not valued.

The collapsed pedestrian bridge provides the visual metaphor: it looked good when it was completed but it did not have the foundation to sustain the stream of people who would cross it --akin to the skilled citizenry required to move a post-industrial society forward?-- and, as such, it broke apart when under stress and must be re-built properly anew with the proper foundation and care.

Development

Using China's mercantilist template as a development model is not the answer for India. One cannot argue with the leaders in Beijing and their ability to manage top-down for their form of mercantilism works at the macro level: China's massive foreign exchange reserve growth is a reflection of an undervalued exchange rate, loan subsidies to its export champions and import restrictions to protect its nascent industries. But if it cannot continue without serious American political backlash in the aftermath of the Great Recession of 2008-09.

The liquidity resulting from China's reserves has been funneled into in a real assets-- we see this in the real estate bubble which will implode one day; unarguably, China is infrastructure ready and has built a world class project management culture --by evidence of the Beijing Olympics, the Shanghai skyline and the myriad "special economic zones" and open coastal cities-- but the continuing sterilization of its monetary reserves cannot go on without ensuing intervention from other countries. In a zero-sum framework of global economic growth, China is screwing its biggest customer by not permitting it to adjust to the disequilibrium in its economy.

In addition, the People's Party Manadarins will face the task of providing a safety net for the citizens. China's economic miracle has been made possible by the tireless toil and sacrifice of its migrant worker; these struggles have been skillfully shown in Fan Xiling's documentary Last Train Home. How long can they be expected to keep going, especially if the target markets fully de-leverage, consumption recedes and the production from the world's factory is no longer required?

Society

Whether one subscribes to the classical liberal view of Peter Bauer or is an adherent to the welfare analysis of Amartya Sen; whether one prefers Paul Collier's top down approach or William Easterly's bottom up focus to economic development, one would have to be in complete denial that economic liberalization has been beneficial to many, specifically the aforementioned middle class in urban centres.

However, most in the country remain desperately poor and are in a worse state of affairs despite liberalization; they have been left off the growth track and in the zeal to placate a corporatist model of development, there has been (in the words of David Harvey) an accumulation by dispossession template followed in rural India which has not benefited society's underclass. The Maoist rebellions in India will not magically go away. Current Indian Prime Minister, Manmohan Singh belatedly admitted:

"We cannot overlook the fact that many areas in which such extremism flourishesare under-developed and many of the people, mainly poor tribals, who live in theseareas have not shared equitably the fruits of development. It isincumbent upon us to ensure that no area of our country is denied the benefitsof our ambitious developmental programmes ."

This is a positive step yet the fear is that the focus will continue to be on the terrorist activities of the Maoist rebels rather than on the narrative, which Sudeep Chakravarti, author of Red Sun: Travels in Naxalite Country, argues should be focused on the failings of the nation, where the disconnect between urban and rural India on matters political, economic and social has given rise to the manifestation of extreme-Left wing movements amongst the rural poor.

The reaction from India's media has centered on shame and excuses but some good can come out of the Commonwealth Games fiasco: here are two thoughts that are worth noting from two different worlds: business and humanities.
The first, again from Harvard Business School’s Michael Porter, on the behaviour required of its political and business elites:
“India needs to learn to be more self-critical, more open, and much more honest about what needs to be done.”

The second from Quentin Skinner, Professor of the Humanities at Queen Mary, University of London, citing Cicero in describing the values that potential leaders require is aimed squarely at the country's political class:
“a willingness to subordinate our private interests to the public good; a desire to fight against corruption and tyranny; and an ambition to reach out for the noblest goals of all, those of honour and glory for our country as well as for ourselves”

Wednesday, September 22, 2010

Commonwealth Games 2010: India is not ready for prime time

Misquote of the week

“These rooms are clean to both you and us. However, it may not appear so to
some others. They want certain standards in hygiene and cleanliness which may
differ from our perception,”

Lalit Bhanot, Official spokesperson and Secretary General for Delhi 2010 Commonwealth Games.

A wake-up call

Before a bridge collapsed near the Delhi’s Commonwealth Games venue and the Commonwealth Games Federation (CGF) gave the Delhi 2010 organizers a day to clean the athlete’s village due to its accommodations being “absolutely filthy”, few outside India and even fewer outside of the Commonwealth –a last remaining shard of the shattered British Empire – had heard of Lalit Bhanot.

Hopefully, they will have to neither hear of nor hear from him again. But that misses the point, for Mr. Bhanot is an archetype all too familiar to those hailing from South Asia: the argumentative, cocksure, dismissive bureaucrat who is wholly incapable of instilling a modicum of confidence in his ability to keep his word and execute in an efficient, effective, transparent and incorruptible manner.

Moreover, the collapsed bridge and unsanitary conditions in the Athlete’s village juxtaposed against the outward veneer of exclusive residential real estate and gated communities – Emaar Properties has used the tag line “A historic address for those shaping India’s future” to sell these properties after the games– are metaphors for the two India’s.

India shining or slumming?

One comprises a 300 million strong middle class – ostensibly well educated, often with marketable technical skills – which grows affluent and fat (due to a stressful, sedentary lifestyle) in the urban core, the other comprises a rapidly growing underclass that is uneducated, illiterate and malnourished and in the extreme cases – when abetted by foreign agencies – taking up arms in a class struggle as Maoist (also referred to as Naxalite) insurgents in the rural peripheries.

Scratching beyond the surface:

Why should you care about Bhanot’s verbal incontinence?

You should care because his comments, as defensive and narrow minded as they were hide some tough truths of reality that bolster the argument that the 2010 Commonwealth Games made no sense for Delhi.

Public health: you should know that in addition to its teeming masses, India has an incomprehensible public sanitation problem – 700 million Indians have no toilets in their homes – which translates to breeding ground for illness during the monsoon season thanks to an absent civic infrastructure. Jason Gale reported on India's sanitation crisis in the March 2009 edition of Bloomberg Magazine.
Hype vs. reality: you should know that despite Nandan Nilekani and Thomas Friedman’s belletrist tomes, India is clearly not shining for those teeming masses. Perhaps if you have “Imagining India: Ideas for the New Century” and “The World is Flat: A brief History of the Twenty-First Century” in your library collection, you may want to replace them with Aravind Adiga’s “The White Tiger”, that offers and insightful glance into the world of the “Half-Baked Indian” who must claw and scratch, just like the chickens in wire coups waiting to be slaughtered in Old Delhi’s open air market, in order to navigate the dog eat dog world that is modern India.

India or China: you should know that despite (the 19 August 2010 edition of) The Economist newspaper’s provocative “Contest of the Century” profiling India and China, and their strained relationship, this is not a true contest; were it a race, China would have lapped India. Some say that India's leadership undertook the task of hosting the Commonwealth Games in order to show that the country 'had arrived' but given the country's populace cares more about cricket than the Commonwealth, and engineers get paid more for writing computer software code over pouring concrete in large infrastructure projects, it was not the right time for this undertaking.

Economic development: it must be evident to a policy maker that China is at least 20 years ahead in terms of economic development as the neoliberal ethos took hold in the corridors of power of the People’s Party despite the politburo’s putative commitment to communism. Under Deng Xiaoping’s economic reforms, China’s coastal regions became tomorrow’s global centers of industry and commerce that are ready to lead the world today while in India, according to Michael Porter, the strategist every MBA student knows, “Indian firms face a really compelling logistical disadvantage over companies in China in terms of getting goods and services to market.”

Political reality: you should finally understand the inherent frustration of the Indian populace when it comes to their performance of their leaders in the Indian political class; they don't trust them but in keeping with their identities, they vote in a block fashion come election time.

The Commonwealth Games has provided a mirror to the corruption endemic in the country and the incompetence in undertaking infrastructure projects when the right individuals are clearly not in place until crisis mode takes hold. Furthermore, it has shed light on the excrement (literally and figuratively) that people become desensitized to as they go about their daily lives looking out for themselves.

The nation's promise

Ironically, the bureaucratic elites in India are populated with talented individuals, skilled at the highest levels and the nation's most selective institutions produce polished professionals able to make meaningful contributions to all sectors of society. However, within the government machinery framework, it is the lack of governance that permits an unremarkable legion of middling and lower level bureaucrats who simply cannot deliver the goods; these Commonwealth games have shown that despite India’s incomparable promise --in terms of opportunities in all manner of infrastructure, education at the primary, secondary and tertiary levels, and a demographic dividend that is the envy of many nations facing increasing dependency ratios-- it is very clearly not ready for prime time and will not be until a cultural shift takes hold.